Why is Zero Co-Pay Important in Health Insurance? Know When You Don't Have to Pay Out-of-Pocket
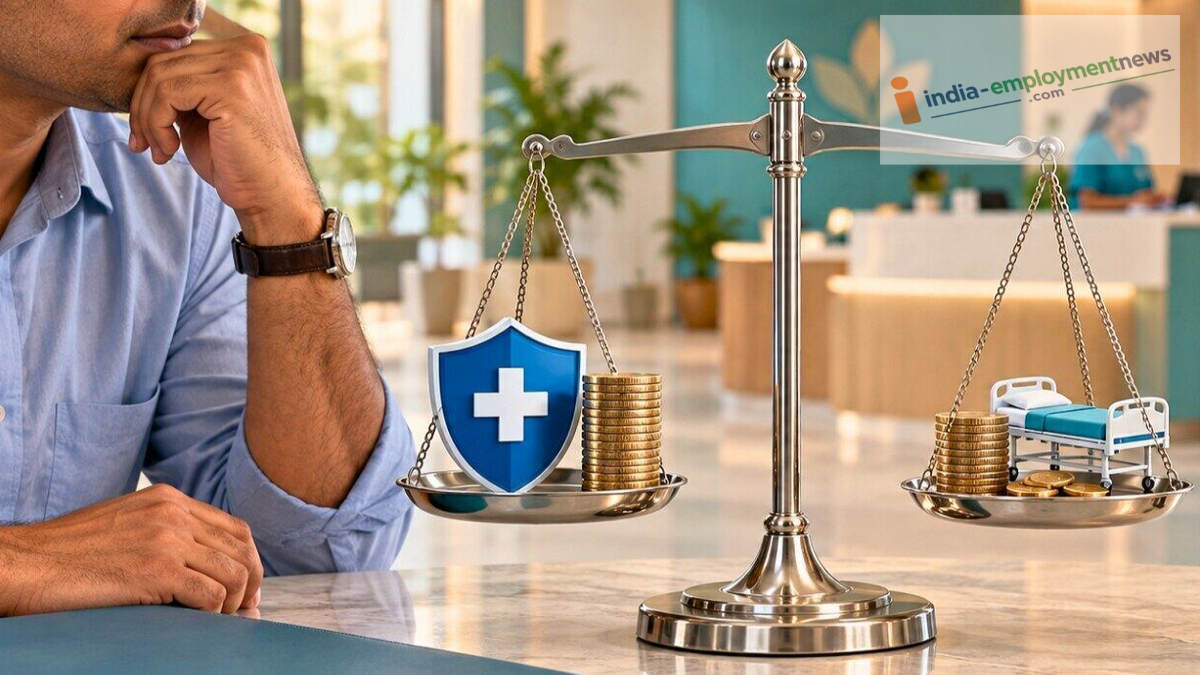
When purchasing health insurance, do not focus solely on the premium and sum insured; understand the co-pay clause as well. With a Zero Co-Pay feature, you do not have to pay a fixed share of an eligible claim out of your own pocket, though not every hospital expense is covered.
If you are planning to buy health insurance for yourself and your family, choosing a policy based only on the premium and sum insured is not enough. It is crucial to understand how much you might have to pay out-of-pocket in the event of hospitalization. In this context, understanding the Zero Co-Pay clause is essential.
Essentially, co-payment (or co-pay) means you are required to pay a fixed portion of the eligible hospital treatment costs yourself, while the remaining amount is covered according to the policy terms. With a Zero Co-Pay feature, you do not have to pay this fixed share out of your own pocket. However, this does not mean the insurance company will cover every single hospital expense.
Why is Zero Co-Pay Important?
In a standard policy, you might have to pay a fixed share of the claim yourself. For instance, if your treatment costs ₹5 lakh and your policy has a 20% co-pay clause, you might have to pay ₹1 lakh out-of-pocket (excluding other deductions), while the insurance company covers the remaining ₹4 lakh as per policy rules. Conversely, if you have a Zero Co-Pay policy, you would not have to pay that 20% share on an eligible claim of ₹5 lakh.
It can reduce out-of-pocket expenses during hospitalization.
It can alleviate financial stress caused by sudden, large medical bills.
This feature can be particularly beneficial for individuals who may require frequent medical treatment.
When do you not have to pay out-of-pocket?
If the claim is approved in accordance with the policy terms and the treatment falls under covered expenses, you will not have to make any payment due to the 'Zero Co-Pay' feature. However, it would be incorrect to assume that the insurance company will cover 100% of the hospital bill simply because of the Zero Co-Pay feature. You may still be required to pay for treatments not included in the policy, items excluded from coverage, and expenses exceeding the sum insured.
Be sure to check the following points when purchasing health insurance:
The total premium of the policy.
The sum insured.
The circumstances under which co-pay applies.
Whether there is a limit on room rent.
The duration of the waiting period.
Which treatments and expenses are excluded.
The number of network hospitals available in your vicinity.
The terms and conditions related to claims.
Whether a different co-pay applies based on age, location of treatment, or specific conditions.