What is 'Pay-As-You-Drive' car insurance, and who actually saves money with it?
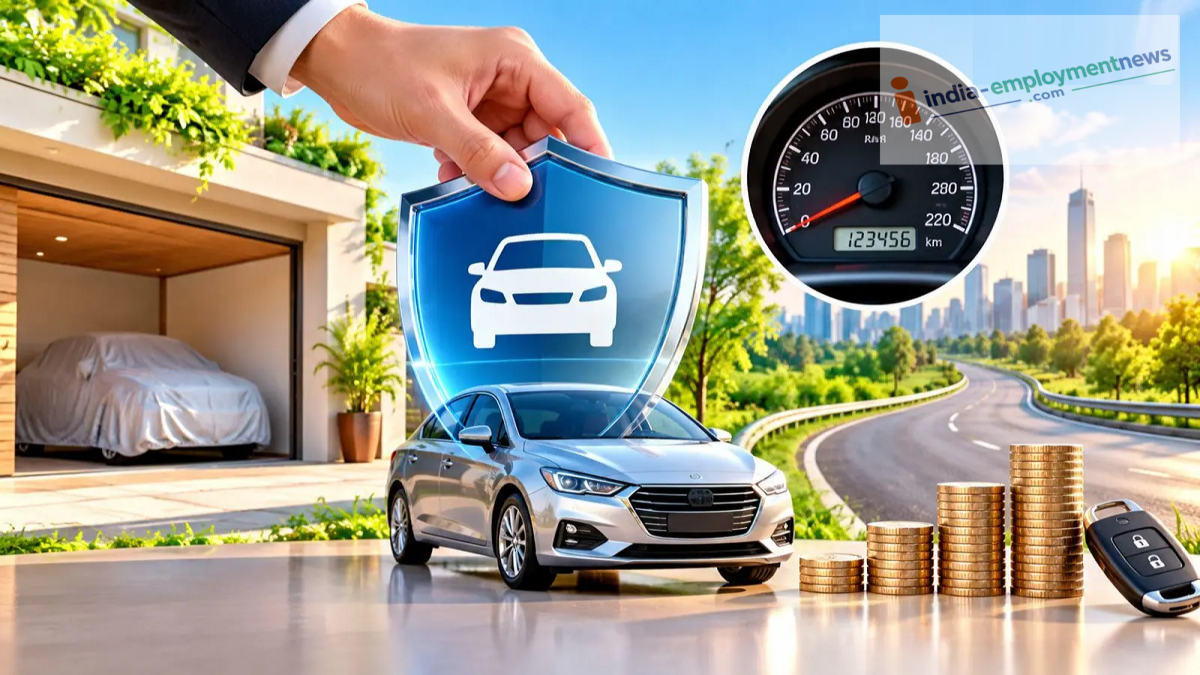
If your car remains parked most of the time and covers fewer kilometers annually, 'Pay-As-You-Drive' car insurance could be beneficial for you. Under this scheme, a portion of the premium is determined based on your expected driving distance. However, the actual savings depend on factors such as the car's value, the chosen mileage slab, and the policy terms.
Your car might stay parked most of the time because your office is nearby, you work from home, or you rely on public transport. Yet, despite this limited usage, your insurance renewal cost often remains unchanged. This can be frustrating—until you learn about 'Pay-As-You-Drive' insurance plans designed to help drivers like you. However, it does not always result in significant savings; we will discuss this in more detail later.
How does 'Pay-As-You-Drive' insurance actually work?
In July 2022, the Insurance Regulatory and Development Authority of India (IRDAI)—the regulator for insurance companies—permitted general insurance providers to offer 'Pay-As-You-Drive' as an add-on to the 'Own Damage' component of motor insurance policies.
With this type of insurance, you estimate the distance you expect to cover over the year and select a corresponding mileage slab. These slabs typically start at around 2,500 km and increase in increments.
Verification is based on your car's odometer reading; a photograph is taken when the policy begins, and another is taken when you file a claim or renew the policy.
While most people estimate the mileage slab, it is better to refer to service invoices from the previous year, as they record the odometer reading. You can easily calculate your actual driving distance by comparing the odometer readings from your last two service visits.
Staying within your mileage limit results in immediate savings, as the discount is applied to the initial premium cost.
Which part of your premium is eligible for the discount?
Every motor insurance policy consists of two components.
The first is liability cover for third parties; the cost for this is determined by the government, not the insurer. For any private petrol or diesel car with an engine capacity of up to 1000cc, the base annual rate is ₹2,094 (excluding 18% GST). Whether you drive 2,000 km or 40,000 km, the cost of third-party car insurance remains the same.
The second component is 'Own Damage' cover, which pays for repairs to your own vehicle. This is the area where most insurance companies compete on price. These discounts apply only to the 'Own Damage' portion of your policy, not the mandatory liability component. This means that no matter how little you drive, there will always be a minimum floor price for your total premium.
Who actually benefits from 'Pay-As-You-Drive' insurance?
Your savings depend on the value of your car. Insurance companies determine the cost of 'Own Damage' coverage based on your car's current market value, known as the Insured Declared Value (IDV).
Consider two families that each drive about 4,000 km annually: one owns a new sedan as a secondary vehicle, while the other uses an older hatchback for all their driving needs.
Even though both cover similar short distances, the owner of the expensive car saves more because their initial insurance premium is higher. The owner of the cheaper, older car saves less—often just enough to cover the cost of a single tank of petrol. If you haven't made any insurance claims, your initial premium is already lower. The insurance company first deducts your No Claim Bonus (NCB) and then calculates the distance-based discount on that reduced amount.
Apart from low mileage, another factor that works to your advantage is owning an expensive car that remains parked for most of the time.
The premium is recalculated at every renewal, so a particularly busy year doesn't lock you into the wrong slab for the long term.
What happens if you exceed your kilometer slab?
Rules regarding exceeding the distance slab vary significantly across insurance companies; therefore, reading the policy carefully before signing it is essential.
Some policies allow you to purchase additional distance mid-year via an endorsement—a written modification added to your existing policy.
Other insurance companies may settle your claim but require you to bear a portion of the repair costs yourself.
Some companies may even completely exclude claims arising from usage beyond the declared distance limit. Even a single long road trip—perhaps to attend a wedding—could exhaust your entire 2,500 km limit. Since you are required to submit a photo of your dashboard when filing a claim, the insurance company can easily verify whether you have driven beyond the limit.
Where this concept doesn't work
The mileage-based discount does not apply to mandatory government charges, which you have to pay regardless. This means there is a minimum policy cost that cannot be reduced, no matter how little you drive. Availability can also vary, as not every insurance company offers this add-on, and the mileage slabs may differ from one company to another. The only reliable way to compare prices is to check quotes for the same driving distance across different providers.
This cover is also not suitable for those with unpredictable annual driving patterns—such as those involving sales visits, job transfers, or travel to another city to care for elderly parents.
Even if you plan to drive significantly less than your declared slab, there is no added benefit; you are charged based on the distance you initially declared.
This insurance plan is best suited for cars that are rarely used. If your car remains parked most of the time, you stop paying for driving capacity you do not utilize, and your low mileage is ultimately reflected in your insurance premium.