Stop your SIP, but your money will still grow: How can a ₹1 crore fund become ₹3 crore in 10 years?
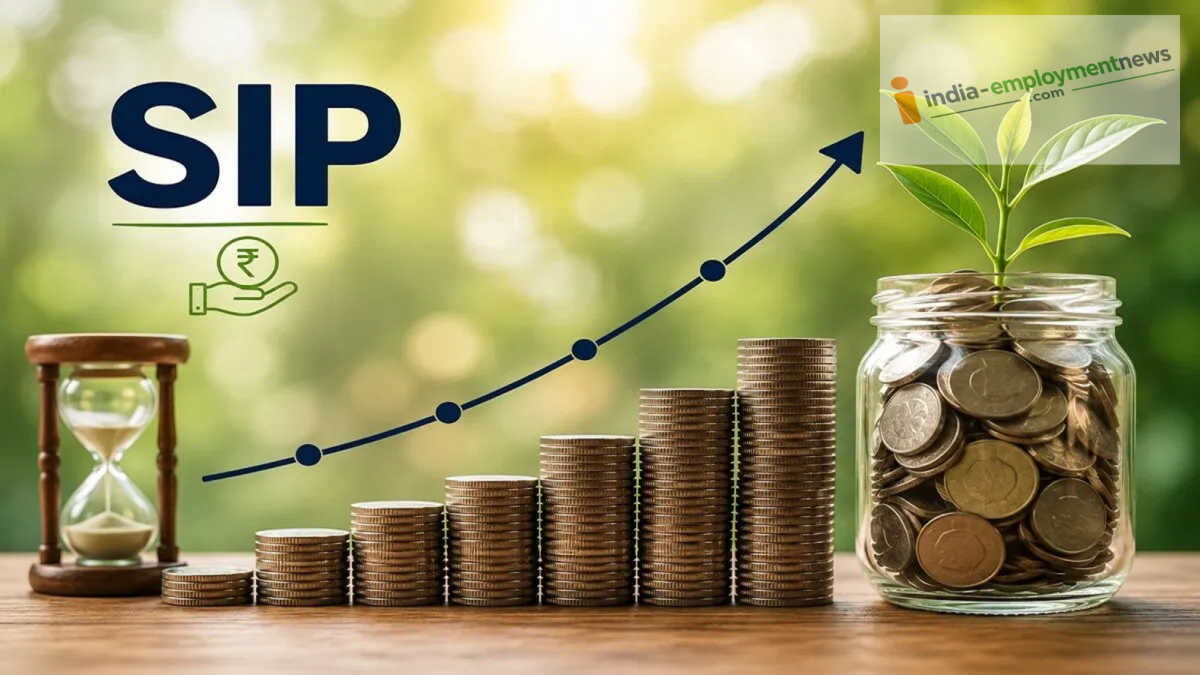
If you have built a fund of ₹1 crore through SIPs, the biggest question arises: should you continue investing or not? Find out what the best course of action is.
Nowadays, people save for their future in various ways—ranging from Fixed Deposits (FDs) to Systematic Investment Plans (SIPs)—so that these savings can cover essential expenses after retirement. If you have invested via SIP and accumulated a fund of ₹1 crore by the age of 40, you might wonder: is it better to keep investing, or will stopping the SIP cause the money to stop growing? If you have this question in mind, here is the answer.
The answer is no. Stopping your SIP does not mean your money will stop growing. If you have already accumulated a corpus of ₹1 crore, that amount can continue to generate returns even if you do not make any new SIP contributions.
Money continues to grow even after stopping SIPs
The key point is that the returns earned over time are added to the existing fund, and you can earn returns on that increased amount as well—a process known as compounding. This clearly means that even if you do not invest any further capital, your ₹1 crore fund will continue to grow.
How can a ₹1 crore fund become ₹3 crore in 10 years?
Let’s look at a simple example:
Initial amount: ₹1 crore
Investment period: 10 years
Age: 40 to 50 years
Estimated annual return: 12%
Estimated return over 10 years: Over ₹2 crore
Estimated fund value at age 50: Over ₹3 crore
In other words, a sum of ₹1 crore can grow to over ₹3 crore in 10 years, assuming an annual return of 12%. Will everyone receive a fund of ₹3 crore?
The biggest question now is whether every investor will receive a fund exceeding ₹3 crore; in reality, that is not the case at all. There are several reasons for this, such as:
The return earned on an investment fluctuates based on market conditions.
The amount of accumulated wealth you receive depends on where you have invested your money.
Several other factors come into play, so assuming that everyone will receive the same return is incorrect.
Returns can vary from person to person.
Plan according to your age
The most important point is that needs change as you age; for instance, your requirements at age 40 will differ from those at age 50. Therefore, investment planning should take into account your future needs as time progresses. Furthermore, do not focus solely on growing the fund; also consider the amount of money that might be required later for your children's education, medical expenses, and other necessities.