Health Policy: Even with a health insurance policy, you may sometimes have to pay a portion of the hospital bill out of your own pocket..
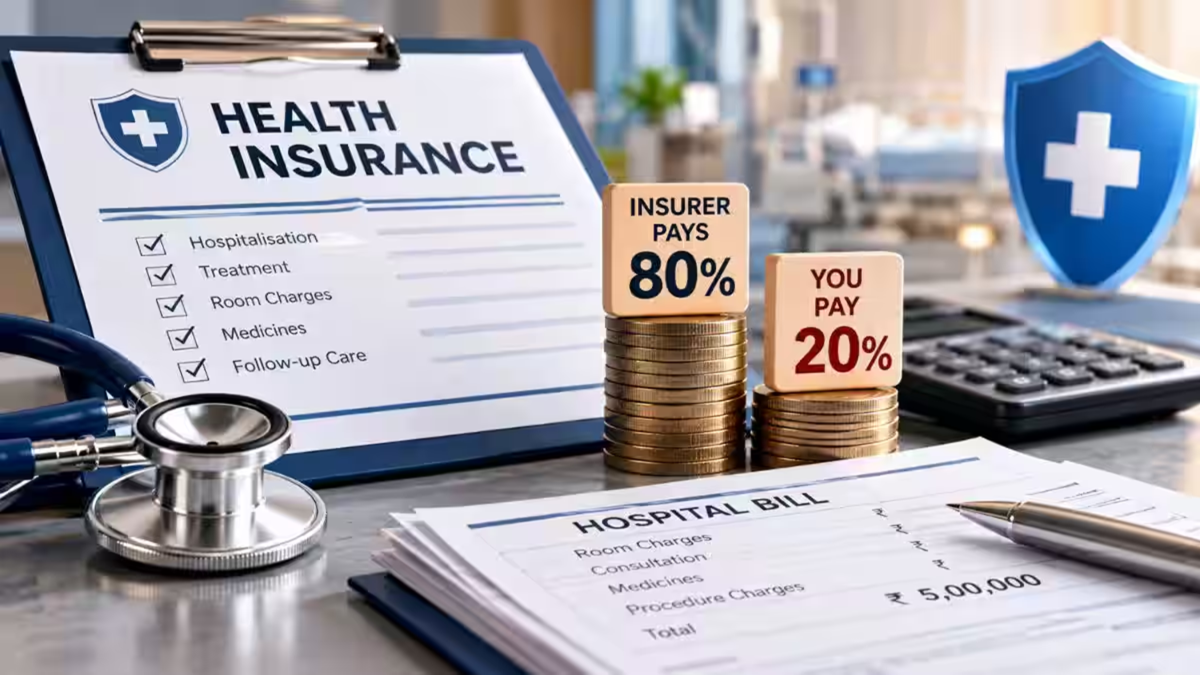
Even with a health insurance policy, you may sometimes have to pay a portion of your hospital bill out of your own pocket. If you find yourself needing to pay ₹3 lakh from your own funds, what should you do? Should you use your savings, break a bank fixed deposit (FD), or withdraw money from your Provident Fund (PF)? Moneycontrol posed this question to an expert.
Decisions must be based on the nature of the illness.
Jose Peter, Co-founder and CEO of Arogya Finance, explains that the answer depends on several factors—specifically, the nature of the illness, the expected duration of treatment, and the total cost involved. While some conditions can be treated with a single surgery, others may require repeated hospitalizations.
Review the hospital bill and insurance settlement statement.
He notes that if a hospital bill amounts to ₹5 lakh and you are left to pay ₹3 lakh out-of-pocket—despite having health insurance—it creates a significant financial challenge, especially when the family also needs to cover ongoing expenses like medication and follow-up doctor consultations. In such a situation, it is crucial to carefully examine the hospital bill and the insurance company’s settlement statement. This will help identify which charges were not covered by the insurance policy.
Many hospitals offer interest-free medical EMIs
As a first step, you can ask the hospital if they offer interest-free medical EMIs, where the hospital itself bears the cost of the interest. If this facility is available, it is the best option for the family. To manage the monthly installments, the family could consider cutting back on non-essential expenses. Only if the hospital does not offer such a facility should you consider alternatives, such as breaking a bank fixed deposit or exploring other financial options.
Things to Consider Before Breaking a Bank Fixed Deposit (FD)
If it becomes necessary to break a bank fixed deposit (FD), you must first assess the potential loss in interest and the penalty applicable for premature withdrawal. Taking a loan against the FD could be a viable alternative. However, if the FD is for a long tenure, breaking it might prove to be the more cost-effective option. You and your family should evaluate both possibilities before making a decision.
The Option of Withdrawing Funds from the EPF
A third option is to withdraw money from your Employees' Provident Fund (EPF). It is important to note, however, that withdrawing from the EPF will impact your retirement savings. Furthermore, this process can be time-consuming. This option may not be practical if a patient is currently hospitalized and the hospital bill must be settled before they can be discharged and taken home; in such a situation, one cannot afford to wait for the EPF withdrawal process.
Combining Options Based on Your Needs
After considering the aforementioned alternatives, the best approach might be to use a portion of your existing savings to pay the hospital bill, while arranging the remaining funds from other sources. This ensures that you are not left completely without cash, leaving some funds available for the patient's ongoing care even after they are discharged from the hospital.
Disclaimer: This content has been sourced and edited from NDTV India. While we have made modifications for clarity and presentation, the original content belongs to its respective authors and website. We do not claim ownership of the content.