Bring your Aadhaar, take home a phone! Is buying a mobile on loan a smart deal, or a heavy burden on your pocket? Find out.
The trend of purchasing smartphones on easy installments by simply presenting an Aadhaar card and a PAN card is growing rapidly. Learn how this financing scheme works and what hidden risks it carries.
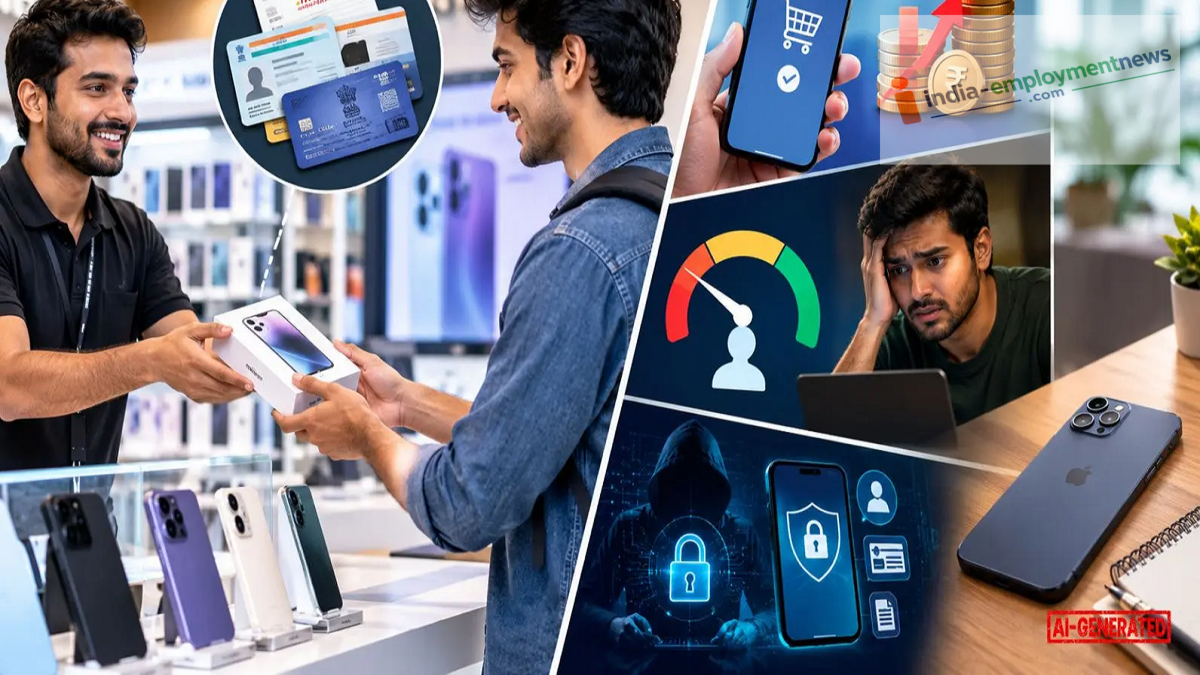
Nowadays, everywhere—from local markets to social media—you’ll come across an eye-catching advertisement: "Bring your Aadhaar card and take home your favorite smartphone on easy installments." For today’s youth and the average person, it has become incredibly easy to walk away with a new phone by simply showing an ID card, without needing a hefty down payment.
But is this "phone-on-loan" model truly a blessing, or does it harbor hidden dangers that could wreck both your budget and your CIBIL score? Let’s explore how this entire system functions and what crucial factors you must consider before buying a phone this way.
How does this "phone-on-loan" ecosystem work?
This facility is now widely available, ranging from local mobile shops to major online platforms. To entice customers, companies offer terms that seem very convenient:
Required Documents: To take advantage of such offers, you generally need an Aadhaar card (linked to your mobile number), a PAN card, bank account details, and a good CIBIL score (typically 750 or higher).
Finance Companies and Apps: Through providers like Bajaj Finserv, Home Credit, Moneyview, or various digital lending apps, a loan or credit limit can be approved in just a few minutes. Local retailers also facilitate this process by completing the necessary paperwork on the spot and handing over the phone immediately.
Where do the complications arise with "easy installments"?
While it may appear very simple, there are several aspects that you must carefully consider:
Hidden Charges: Often, offers like 'No Cost EMI' or zero-interest schemes are used as bait; however, customers may end up paying significant amounts through processing fees, GST, and other hidden charges.
Damage to CIBIL Score: Missing an EMI payment—even by mistake—directly impacts your CIBIL score. This could hinder your ability to secure future bank loans, in addition to incurring heavy penalties.
Privacy and Security Risks: Before sharing personal information (such as Aadhaar or PAN card details) with any unfamiliar or untrustworthy app, always verify the company's legitimacy; otherwise, you could fall victim to data leaks or fraud.
Choose Authorized and Reliable Stores
Everyone enjoys buying a new smartphone, but taking out a loan to purchase one—solely for the sake of appearances—while jeopardizing your financial stability is not a wise decision. If a purchase is truly necessary, opt for an EMI plan only through an authorized, reliable store or a registered finance company. Always read the 'Terms & Conditions' thoroughly before signing any documents to avoid any future regret.