SBI Surya Shakti Solar Finance Scheme: Get ₹4 crore for solar panels; SBI's bumper offer for business owners..
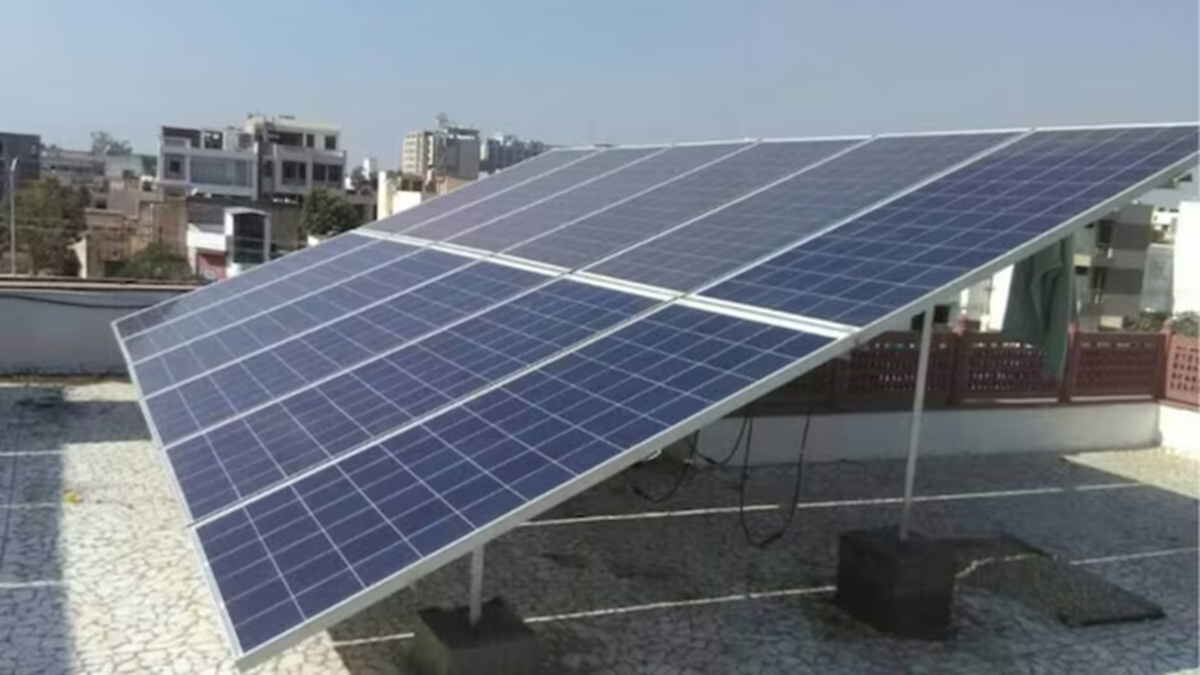
If you are considering installing solar panels, there is good news for you. The State Bank of India (SBI), the country's largest public sector bank, has launched a special loan scheme named 'Surya Shakti Solar Finance' to promote solar energy. Under this scheme, customers such as business entities, MSMEs, and housing societies can avail loans from the bank to install solar power systems.
Solar plants can be installed on rooftops or on the ground. This can help reduce electricity costs. According to SBI, the scheme specifies different loan limits and repayment tenures for various types of solar projects. In some cases, benefits such as interest subsidies may also be available. Here are the details regarding this scheme.
What is SBI's Surya Shakti Solar Finance Scheme?
The objective of this SBI scheme is to provide financial assistance for installing grid-connected solar power systems. Loans are available for both rooftop and ground-mounted solar plants. This scheme is specifically designed for businesses, MSMEs, and housing societies that wish to install solar systems to meet their electricity requirements.
Some projects may also include arrangements to sell the electricity generated by the solar plant to a third party. In other words, the scheme can be utilized not only for meeting one's own electricity needs but also for other types of projects.
What is the loan amount available?
For captive solar projects, term loans of up to ₹10 crore can be granted to MSMEs, business entities, and cooperative housing societies. Customers are required to contribute a minimum of 20% of the project cost themselves. The maximum repayment period is 10 years. Meanwhile, for other types of solar projects, the loan limit is set at up to ₹50 crore. In these cases, the customer must contribute at least 25% of the amount. The tenure for such loans can extend up to a maximum of 15 years, which may include an initial moratorium period as per the stipulated terms.
Let’s understand this with an example—
Suppose an MSME needs ₹5 crore to set up a solar plant. For a captive solar project, the entity must contribute at least 20% (i.e., ₹1 crore) from its own funds, while the remaining ₹4 crore can be obtained as a loan from SBI. The repayment period for this loan can extend up to a maximum of 10 years. Similarly, if another solar project costs ₹20 crore, the customer must contribute at least 25% (i.e., ₹5 crore) upfront, and a loan of ₹15 crore can be availed. The tenure for such a loan can be up to 15 years.
What are the benefits regarding interest rates and subsidies?
Under this scheme, the interest rate is determined based on the customer profile and the loan category. According to News18 Telugu, the interest rate could be around 9% in certain cases. A bank official stated that eligible customers might receive an interest subsidy of 4%. Consequently, with the subsidy applied, the effective interest rate for the customer could be around 5%. For MSMEs, the interest rate may be linked to the EBR (External Benchmark Rate), whereas for non-MSME customers, the rate could be linked to the 6-month MCLR (Marginal Cost of Funds-based Lending Rate).
What are the conditions for availing the loan?
To avail the benefits of this scheme, certain mandatory conditions must be met. Customers applying under the 'captive' category must have a CIBIL score of at least 650. The MSME unit is also required to possess a valid business registration number. The solar system must be grid-connected. Additionally, the EPC (Engineering, Procurement, and Construction) company installing the solar plant must be registered with the relevant government authority or DISCOM (Distribution Company).
No charges for early loan repayment
SBI’s scheme also offers relief to those who repay their loans early. According to available information, no prepayment charges will be levied if the customer repays the loan before the scheduled time. Separate conditions apply to cooperative housing societies; such societies are required to provide a 25% cash margin, and personal guarantees from promoters may also be required. However, under bank norms, an additional guarantee may not be required if sufficient security is available.
SBI's Surya Shakti Solar Finance scheme offers businesses and entities the option to avail of a loan for setting up solar plants. However, before taking the loan, the customer should thoroughly understand the interest rate, their own contribution, security requirements, and payment terms.
Disclaimer: This content has been sourced and edited from TV9. While we have made modifications for clarity and presentation, the original content belongs to its respective authors and website. We do not claim ownership of the content.